
Yes, superannuation affects your Age Pension, but the rules shift once you reach Age Pension age (currently 67). Before that, super sits outside the pension system entirely. After it, Centrelink counts your balance under the assets test and applies deeming rules under the income test. Check Services Australia's calculators or get personalised modelling before you make any big withdrawal or start an income stream.
TL;DR:
- Super balances are counted as assets under the assets test once you reach Age Pension age, with no special exemptions, potentially reducing your pension.
- Drawing large lump sums from super can increase assessable assets or trigger deeming, sometimes offsetting the cash benefit of withdrawal.
- Matching your withdrawal and pension claim timing is crucial, with strategies including deferring the pension or maintaining a small super balance to optimize income.
- Age is the primary eligibility factor, requiring you to be at least 67, and residency rules may affect your qualification for the Age Pension.
- A personalized scenario model, rather than generic rules, is essential to determine the best sequencing of super drawdowns and pension claims for your household.
- ✓Retirement planning
- ✓Superannuation advice
- ✓Age Pension strategies
Table of Contents
- How super and the Age Pension work together
- When can you access super, and when do you qualify for the Age Pension?
- How Centrelink counts your super under the assets and income tests
- Three common ways retirees blend super and the Age Pension
- A checklist before you touch your super or start a pension
- Amber Wealth perspective: practitioner notes from a retirement planner
- What else determines Age Pension eligibility besides your super?
- How your Age Pension payment amount is actually calculated
- Common misconceptions about super and the Age Pension
- Recent changes shaping how super and the Age Pension interact
- Couples versus singles: how the rules differ
- Timing your super withdrawals and pension claim well
- The gap between the rules and how people actually plan
- How Amber Wealth can help you plan the transition
- Sources
- FAQ
How super and the Age Pension work together
Super is your own money, built up through compulsory contributions and, often, salary sacrifice over a working life. The Age Pension is different in kind: it is means‑tested government support, funded through general taxation and designed to top up or replace private income for people who need it. Most Australians retiring today will draw on both at some point, just not always at the same time or in the same proportion.
The mix tends to shift as retirement progresses. Someone retiring at 60 with a solid super balance might live off super alone for several years, then transition onto a part Age Pension once their balance runs down and they reach Age Pension eligibility age. Someone with a smaller balance might qualify for a substantial pension almost immediately and use super as a supplementary top‑up.
Broadly:
- Retirees with larger super balances (often those who owned a business, worked in high‑income professions, or salary sacrificed consistently) tend to rely primarily on super, at least initially.
- Retirees with smaller balances, broken work histories, or single‑income households often rely more heavily on the Age Pension from an earlier stage.
- Most people land somewhere in between, and that position can move year to year as balances draw down and asset values change.
Timing matters more than most people expect. Drawing super down too fast in the early years can push someone onto the Age Pension sooner than planned, while being too conservative can mean paying more tax than necessary on investment earnings outside super. Services Australia and the ATO both publish detailed, current guidance worth checking before locking in a strategy.
When can you access super, and when do you qualify for the Age Pension?
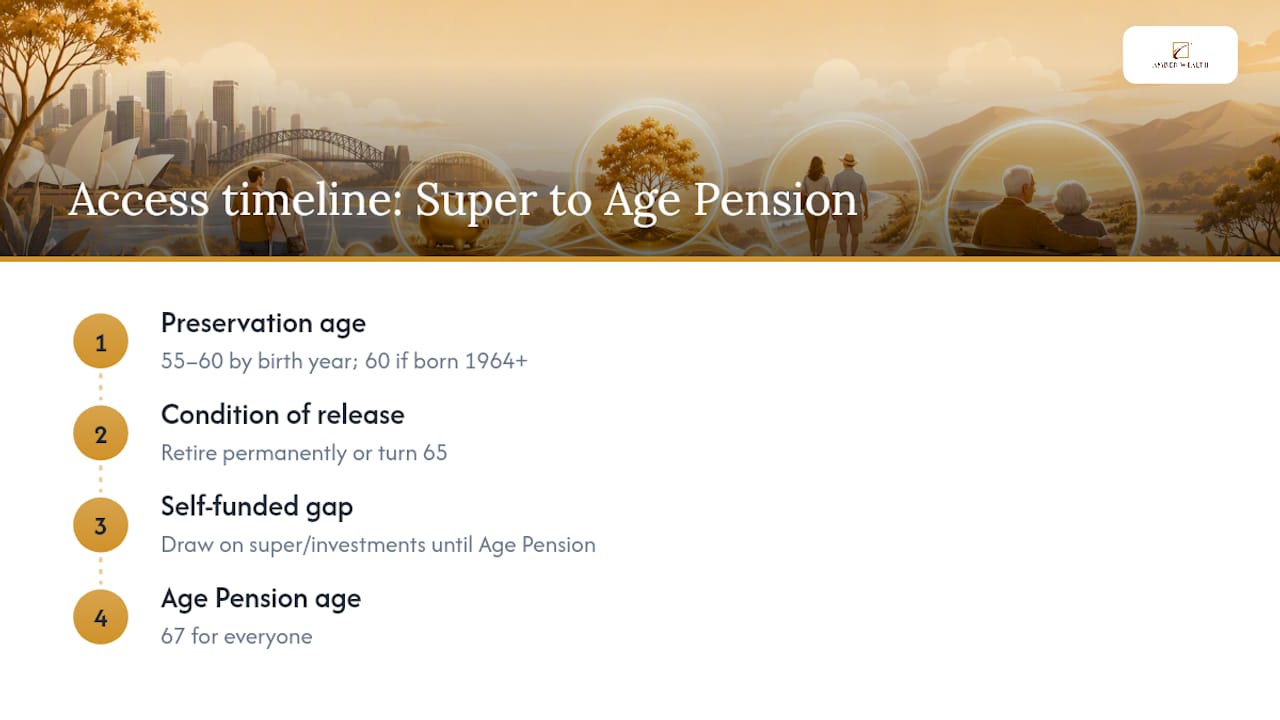
Two separate clocks run here, and confusing them is a common mistake. Preservation age is when you can generally access your super, and it sits between 55 and 60 depending on your birth year, with 60 now the preservation age for anyone born after June 1964. Reaching preservation age alone isn't enough. You also need to meet a condition of release, most commonly retiring permanently from the workforce, or turning 65, which allows access regardless of your work status.
Age Pension age is currently 67 for everyone, having risen in stages from 65. That's a gap of up to a decade between when you can touch your super and when the Age Pension becomes available. This income gap needs deliberate planning. Many people retire from full‑time work in their late 50s or early 60s and rely entirely on super, investments, or part‑time income until the Age Pension kicks in, which makes drawdown pacing genuinely important.
How Centrelink counts your super under the assets and income tests
Once you reach Age Pension age, super stops being invisible to Centrelink. Two tests run in parallel, and Services Australia applies whichever produces the lower pension amount.
The assets test counts your super balance as an asset, using the figure from your latest super statement. It sits alongside your home (if above the exempt threshold value), investments, and other assets. There's no special exemption for super once you're over Age Pension age, unlike when you're under it, when super in accumulation phase is generally excluded.
The income test treats account‑based pensions differently. Rather than assessing the actual income the pension generates, Services Australia applies deeming, a set of assumed rates applied to your financial assets regardless of what they actually earn.
Deeming, explained simply: Centrelink assumes your financial assets earn a fixed rate of return, and uses that assumed figure for the income test, not your actual investment performance. This has applied to account‑based pensions since 1 January 2015.
A few practical points worth knowing:
- Centrelink runs both tests and pays based on whichever result gives you the lower pension, so you can't assume the assets test is the only one that matters.
- Account‑based pensions started before 1 January 2015 may carry grandfathering, particularly relevant for Commonwealth Seniors Health Card holders, where the older, more favourable income test treatment can still apply.
- Getting this wrong is easy if you're relying on general online calculators rather than checking your specific product and start date.
Three common ways retirees blend super and the Age Pension
Most retirees fall into one of three broad patterns, and recognising which one fits your situation helps frame the decisions ahead.
- Super first, pension later. You draw down super to fund living costs in the early retirement years, conserving balances where possible, and transition to a part or full Age Pension once your balance has reduced enough or you reach Age Pension age. MoneySmart outlines this as one of the most common approaches for people with moderate to strong super balances.
- Pension plus a top‑up. You qualify for a part Age Pension from the outset and draw smaller, regular amounts from super to supplement it, stretching your balance over a longer period.
- A changing mix. Your split between super income and Age Pension shifts year to year as investment markets move, spending needs change, or personal circumstances (health, housing, relationship status) evolve. This group tends to benefit most from annual reassessment.
Large lump sum withdrawals deserve particular caution. Pulling a big amount from super and holding it in a bank account doesn't remove it from Centrelink's view. It simply moves from one assessable asset to another, and can sometimes make things worse if it triggers deeming on a larger cash balance.
Pro Tip: Before taking a lump sum, model what happens to your assessed assets and income both before and after. A withdrawal that feels like it "frees up cash" can leave your Age Pension assessment exactly where it started, or worse.
A checklist before you touch your super or start a pension
Getting the sequencing right avoids most of the costly mistakes retirees make. Work through this before acting:
- Pull together current statements for super, bank accounts, shares, and other investments so you have an accurate asset picture.
- Run the numbers through Services Australia's payment calculators and check current ATO guidance on withdrawal rules and tax treatment.
- Model what starting an account‑based pension does to your deemed income, and compare that against taking a lump sum instead.
- If you're seeing an adviser, ask directly how a proposed change affects your assets test result, whether it touches your Commonwealth Seniors Health Card or Pensioner Concession Card, and what the tax consequences are.
- Keep written records of any advice, especially around deeming exemptions or grandfathered arrangements, in case Centrelink later reviews your file.
| Step | Why it matters |
|---|---|
| Gather current balances | Centrelink uses your latest statement, not last year's figure |
| Check both tests | The lower result applies, and it's not always the one you expect |
| Model before acting | Deeming and asset reclassification can offset the benefit of a withdrawal |
| Confirm concession card impact | Losing a card can cost more than the pension change itself |
Amber Wealth perspective: practitioner notes from a retirement planner
The pitfalls we see most often at Amber Wealth aren't complicated. They're timing errors: someone draws a lump sum without checking how it reclassifies under the assets test, or starts an account‑based pension without realising deeming will apply from day one. Adam Sobczak, Director at Amber Wealth, notes that scenario modelling, comparing drawdown sequences against deferring to Age Pension age, usually reveals a clearer path than intuition alone. This is general information, not personal advice. Speak with a qualified financial adviser before acting on your own circumstances.
What else determines Age Pension eligibility besides your super?
Superannuation is only one piece of the eligibility puzzle. Age is the starting gate: you need to be 67 or older, regardless of how your super or other assets look. Residency requirements sit alongside this, and they trip people up more often than expected. Generally, you need to have been an Australian resident for at least 10 years in total, with at least five of those years continuous, though exceptions exist for refugees and people who've lived or worked in countries with which Australia has a social security agreement.
Beyond age and residency, Centrelink looks at your relationship status (single or couple), whether you own your home, and your total combined assets and income, including super, property, vehicles, and investments. Home ownership status matters more than most people realise: homeowners face a lower assets test threshold than non‑homeowners, because Centrelink assumes homeowners have less need for a housing‑related buffer.
There's also a work‑related eligibility angle for people who haven't reached Age Pension age but are considering early retirement. You can't claim the Age Pension early simply because you've stopped working, even if you've accessed your super under a condition of release. The two systems run on entirely separate clocks, which is part of why the income gap between preservation age and Age Pension age needs its own funding plan rather than an assumption that one flows automatically into the other.
How your Age Pension payment amount is actually calculated
Your payment isn't a single calculation. It's two separate calculations run side by side, with Centrelink paying whichever produces the lower amount.
Under the assets test, your total assessable assets, including super, savings, investment property, and vehicles, are compared against thresholds that vary depending on whether you're single, partnered, a homeowner, or a non‑homeowner. Exceed the threshold and your pension reduces on a sliding scale; exceed it by enough and you lose eligibility entirely.
Under the income test, your assessable income, including deemed income from financial assets like account‑based pensions, is compared against separate thresholds. Again, homeowner and relationship status change where those thresholds sit.
The result is that two people with identical super balances can receive very different Age Pension amounts, depending on whether they own their home, whether they're single or partnered, and how their assets are structured. A couple who owns their home outright with $600,000 in combined super might receive a different part pension than a single non‑homeowner with the same balance, because the underlying thresholds and living cost assumptions differ. This is precisely why generic online guides can mislead: the maths depends on your specific household structure, not just your bank balance.
Common misconceptions about super and the Age Pension
The biggest myth is that the Age Pension is all or nothing. In reality, most eligible retirees receive a part pension rather than the full rate, calibrated precisely to their assessed assets and income. Believing it's binary leads people to either give up on applying when they'd actually qualify for something, or assume they're locked out permanently when a change in circumstances could shift their entitlement.
A second common misunderstanding is that spending down super to "get under the threshold" is a straightforward win. Money doesn't vanish from Centrelink's assessment just because it's spent on a car, a holiday, or moved into a family trust. Gifting rules specifically limit how much you can give away before it's still counted as an asset for five years. Spending on genuinely consumed items (holidays, home improvements within reason) is different from asset shuffling, but the line isn't always obvious.
A third misconception: many people believe their super is completely ignored until they "retire properly." In practice, once you're over Age Pension age, super in any form, whether left in accumulation or converted to an income stream, is assessed. There's no age‑based exemption once you've crossed that line, only structural differences in how accumulation phase versus a pension phase account gets counted for income test purposes.
Recent changes shaping how super and the Age Pension interact
The most significant structural shift in recent years was the move to deeming for account‑based pensions from 1 January 2015. Before that date, many ABPs were assessed on their actual income, which could work in a retiree's favour when actual returns sat below deemed rates, or against them when returns ran high. Grandfathering provisions still protect pensions started before that date for some Commonwealth Seniors Health Card holders, which is why checking your pension's start date matters before assuming current rules apply.
Age Pension age itself has also shifted over the past decade, rising gradually from 65 to 67, with the increase phased in over several years rather than applied all at once. This has widened the income gap for people who access super at preservation age but must wait longer for the pension, making bridging strategies more relevant than they were for previous generations of retirees.
Deeming rates themselves are reviewed periodically and can move up or down depending on economic conditions, which directly changes how much assessed income an account‑based pension generates under the income test. A rate change doesn't require you to do anything, but it can shift your pension payment without any action on your part, which is worth checking annually rather than assuming last year's figure still applies.
Couples versus singles: how the rules differ
Age Pension thresholds are set separately for singles and couples, and the difference isn't simply double. Combined assets and income for a couple are assessed together, even if only one partner is over Age Pension age, which surprises people who assume their younger partner's super is excluded, it isn't, once the assessment applies to the couple as a unit.
This creates planning complexity when partners are different ages. If one partner is 67 and the other is 62, the younger partner's super still counts toward the couple's combined assets test once the older partner claims the Age Pension. Some couples structure their finances around this, deliberately keeping more in the younger partner's super until they too reach Age Pension age, since super held by someone under Age Pension age in accumulation phase generally sits outside the assets test.
Singles face different thresholds again, generally lower total limits than couples but a correspondingly simpler assessment, since there's no second person's assets or income to combine. Home ownership still changes the threshold for singles just as it does for couples, and a single non‑homeowner has meaningfully more assets test headroom than a single homeowner, reflecting the assumption that non‑homeowners carry ongoing housing costs.
Timing your super withdrawals and pension claim well
The order in which you draw down super and claim the Age Pension can meaningfully change your total retirement income, though the "right" sequence depends heavily on your balance, age gap to Age Pension age, and asset mix. A few patterns tend to recur in practitioner modelling.
Deferring the Age Pension claim while drawing super tends to suit people with larger balances who can comfortably self‑fund the years between preservation age and 67, preserving eligibility for a larger part pension later once the balance has naturally reduced. Claiming early and topping up with modest super withdrawals tends to suit people with smaller balances, where stretching super over decades matters more than maximising it in any single year.
Converting super to an account‑based pension close to Age Pension age, rather than earlier, can sometimes reduce the years spent under deeming assessment, though the deeming assumption applies regardless of whether the account is called "accumulation" or "pension phase" once you're over Age Pension age and it's assessed under the income test. Getting this sequencing right is exactly the kind of calculation that benefits from proper modelling rather than rules of thumb, since deeming rates, personal spending needs, and asset composition all interact differently for each household.
The gap between the rules and how people actually plan
The conventional advice on this topic tends to focus entirely on the mechanics, assets tests, deeming rates, preservation age, and treats the actual decision as if it were a spreadsheet problem. It isn't. The research and guidance from Services Australia and MoneySmart are genuinely good at explaining what happens to your assessment. They're far less useful at helping you decide when to draw down, when to claim, or how much buffer to keep for the years between preservation age and 67.
What gets underestimated is how much the "right" answer depends on sequence, not just balance. Two people with identical super at 60 can end up with very different lifetime outcomes purely because one drew down early and deferred the pension, while the other claimed early and preserved capital. Neither approach is universally correct, and most generic guides don't say that clearly enough.
My honest read: the checklist matters less than the modelling. Ticking boxes on residency and age is easy. Working out whether your specific mix of assets, timing, and household structure produces a better outcome one way or another requires running actual numbers against your situation, not a rule of thumb borrowed from someone else's retirement.
— Adam
How Amber Wealth can help you plan the transition
Working out exactly how your super balance interacts with the Age Pension, and what sequence of withdrawals and claims suits your household, is rarely a spreadsheet exercise you can finish in an afternoon. It depends on your asset mix, your partner's age, your home ownership status, and how deeming rates move over time. Amber Wealth is a Melbourne based alternative to generic online calculators for retirees who want an actual, personalised answer rather than a rough estimate.
Adam Sobczak and the team at Amber Wealth work through scenario modelling with pre‑retirees and retirees across Melbourne's Bayside area and beyond, comparing drawdown sequences, concession card impacts, and Age Pension timing against your specific numbers. If you're within a few years of preservation age or Age Pension age and want clarity before making a move, book a complimentary consultation through Amber Wealth's retirement planning service and get a clear picture of how your super and the Age Pension will actually work together.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Super and the Age Pension — MoneySmart
- Superannuation — Services Australia
- Social Security Guide — deeming and account‑based pensions
FAQ
How much super can I have and still get the Age Pension?
There's no single figure, because it depends on whether you're single or partnered and whether you own your home, and the applicable threshold changes periodically. Check current assets test thresholds through Services Australia before assuming a specific number applies to you.
How does superannuation affect your Age Pension?
Before Age Pension age, super generally sits outside the assessment entirely. After Age Pension age, your balance counts under the assets test, and any account‑based pension is assessed under deeming rules for the income test, with Centrelink applying whichever test gives the lower payment.
How much savings can a pensioner have before it affects their pension?
Savings, including super, count toward the same assets test threshold that applies to all your assessable assets, and the exact limit depends on your homeowner status and whether you're single or partnered. There's no separate, higher allowance just for cash savings.
How much is the full Age Pension currently?
Payment rates are indexed and change periodically, so the current full rate for singles and couples should be confirmed directly through Services Australia's Age Pension payment rates page rather than relying on a figure that may be out of date.
Does starting an account‑based pension change my Age Pension?
It can, because account‑based pensions are assessed under deeming rules for the income test rather than on actual investment performance, and the balance still counts under the assets test. Modelling the specific effect before you start one is the safest approach.
Recommended
- Retirement age Australia: what you need to know
- A retirement planning checklist for people approaching retirement
- Avoid Super Tax After 60 in Australia: ATO Rules, Caps and Checklist
- Age Pension eligibility: age, residency and the income and assets tests
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here. General Advice Warning Disclaimer: The information on this website is general information only and is not intended to be a recommendation. We strongly recommend you seek advice from your financial adviser as to whether this information is appropriate to your needs & financial situation.