
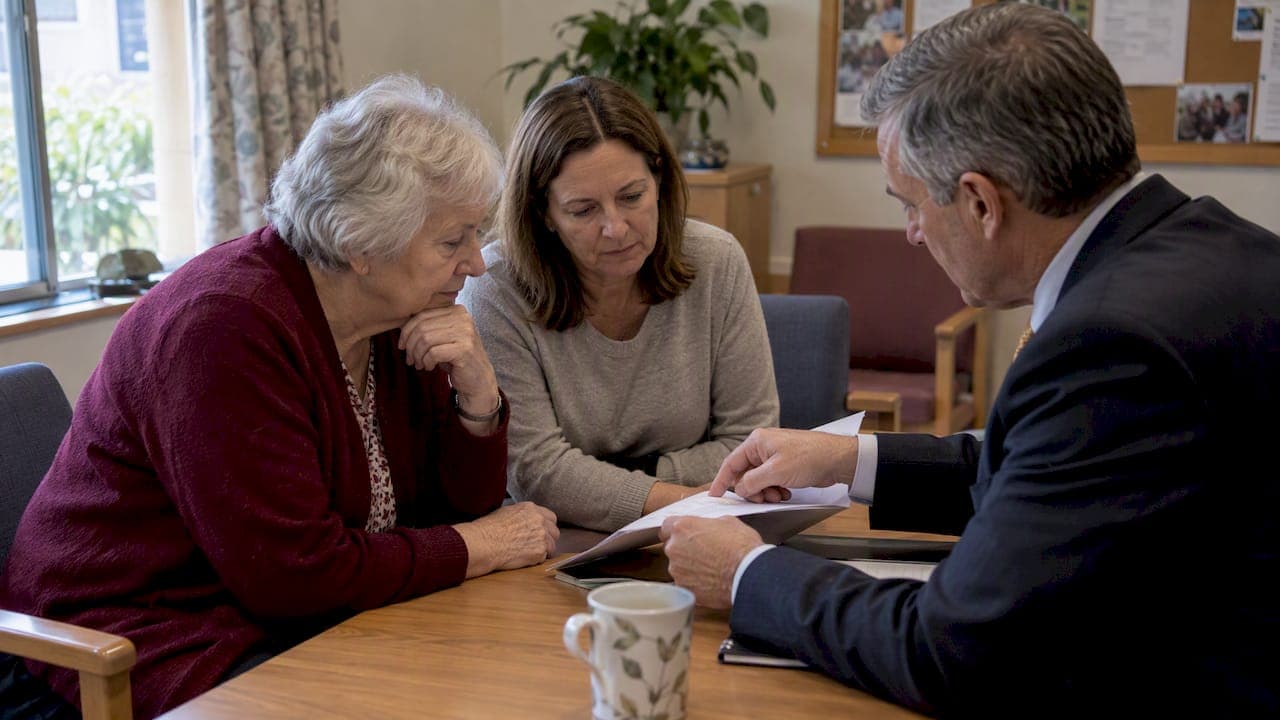
Aged care financial advice helps you map likely accommodation and ongoing care costs, complete a means assessment, and build an Age Pension-safe plan before you sign anything with a provider. The My Aged Care fee estimator and Services Australia's Financial Information Service (FIS) are free starting points. If you're unsure where to begin, request a means assessment or call FIS before talking to a financial adviser such as Amber Wealth.
TL;DR:
- Choosing between a refunding accommodation deposit and a daily payment impacts liquidity, estate plans, and pension eligibility, so understand the specific rates and refund timing.
- Apart from basic daily fees, residents may pay means-tested contributions and additional charges capped over lifetimes, which vary based on income, assets, and care needs.
- Support at Home contributions depend on income and assets, with lifetime caps and protections for those transitioning from previous arrangements; re-assessments can alter payment levels.
- Timing of means assessments, fee negotiations, and signing agreements is critical to avoid paying more than necessary or affecting pension entitlements negatively.
- Proper advice requires verifying adviser credentials, understanding fee structures, and aligning care finance decisions with broader retirement and estate plans.
Table of Contents
- Accommodation costs: RAD, DAP, agreed room prices and interest rules
- Ongoing residential care fees: basic daily fee, non-clinical care contribution and hotelling
- Support at Home (home-care) contributions, caps and 'no worse off' protections
- Means assessments and how they interact with Age Pension entitlements
- Practical planning checklist and timing: what to do and when
- How to choose a financial adviser for aged care: checks, fees and questions to ask
- Amber Wealth: how we approach aged care financial advice
- Tax implications of aged care payments and financial advice
- Procedures and timelines for applying for aged care subsidies and government benefits
- Impact of aged care financial decisions on family members and potential inheritance
- Common financial scams and fraud risks targeting elderly in aged care settings, and how to avoid them
- What practitioners see go wrong most often
- How Amber Wealth can help
- Sources
- FAQ
Accommodation costs: RAD, DAP, agreed room prices and interest rules
Residential aged care accommodation is usually paid one of three ways: a refundable accommodation deposit (RAD), a daily accommodation payment (DAP), or a combination of both. A RAD is a lump sum you pay upfront, similar to an interest-free loan to the provider, which is refunded when you leave care (less any amounts you've agreed to have deducted). A DAP is a daily charge calculated on the unpaid portion of the room price, working more like rent.
Providers set their own room prices, but any price above the threshold set by the Department of Health must be approved. If you choose a DAP instead of paying the full RAD, the unpaid balance accrues at the Maximum Permissible Interest Rate (MPIR). Providers also use a Base Interest Rate (BIR) when calculating refunds or partial payment arrangements. Both rates, along with accommodation supplement thresholds, are published in the Department of Health's schedule of fees and charges, which also sets the accommodation deposit limits providers must work within.
Before signing an accommodation agreement, ask the provider to put the following in writing.
- The exact room price, and whether it sits above or below the government-set threshold requiring approval.
- Whether a combination payment is available and how the RAD and DAP portions would be split.
- How long a refund takes to process after you leave the room, and what deductions (if any) apply.
- Whether the daily accommodation payment is indexed or can change during your stay.
Choosing between a RAD and a DAP isn't just a cashflow decision. A RAD paid from savings reduces liquid assets for means-testing purposes in some circumstances, while a retained RAD balance can affect how your estate is settled later. These trade-offs are specific to your assets, pension status and family situation, so general comparisons only go so far.
Ongoing residential care fees: basic daily fee, non-clinical care contribution and hotelling
Every resident pays a basic daily fee, set as a percentage of the single basic Age Pension rate, regardless of income or assets. On top of that, residents who can afford to contribute more pay a non-clinical care contribution (sometimes described loosely as a "hotelling" charge) that covers things like meals, laundry and cleaning above the basic fee.
**The basic daily fee is set at a specific daily amount, and the non-clinical care contribution carries a daily cap, according to the Department of Health's published fee schedule. These figures sit alongside lifetime caps on means-tested contributions, which are indexed periodically and detailed in the same schedule.
- The basic daily fee applies to everyone and doesn't depend on income or assets.
- The non-clinical care contribution scales with your means assessment outcome, up to the daily cap.
- A means-tested care fee is layered on top for residents assessed as able to contribute more toward their clinical care costs.
- Lifetime and annual caps exist so no one pays indefinitely once they've contributed a set amount.
How much you pay beyond the basic daily fee depends heavily on whether you're a full pensioner, part pensioner or fully self-funded. A full pensioner with modest assets will typically pay close to the basic daily fee alone, while a self-funded retiree with substantial assessable assets and income may pay toward the full non-clinical care contribution cap, plus a means-tested care fee. The only way to know your actual figure is through a completed means assessment, since providers can't set these contributions themselves.
Support at Home (home-care) contributions, caps and 'no worse off' protections

Support at Home, the home-care program that replaced the old Home Care Package model, charges participant contributions based on the type of service and your own income and assets. Contributions are generally split across service categories, commonly grouped as clinical support (where contributions are lowest or nil), independence support, and everyday living support (where contributions are typically highest).
According to the Department of Health's Support at Home contributions guidance, contribution percentages vary by income and asset position, and there are lifetime caps on how much a participant contributes toward their care over time.
- Clinical supports (like nursing) generally attract little to no participant contribution.
- Independence and everyday living supports carry higher contribution percentages for those assessed as having greater means.
- A lifetime cap limits total contributions, after which government funding covers the remainder.
- People who held a Home Care Package before the transition are protected by a 'no worse off' principle, meaning their contributions shouldn't exceed what they would have paid under the old arrangements.
Your contribution rate isn't fixed forever. A change in income, assets or care needs can trigger a re-assessment, which may shift your contribution band up or down. Start with the Support at Home fee estimator on My Aged Care to get a realistic range before committing to a care plan. If contributions become genuinely unaffordable, Services Australia's hardship provisions allow a claim through the SA462 hardship form, which is assessed against your specific circumstances rather than a fixed formula.
Means assessments and how they interact with Age Pension entitlements
A means assessment looks at your assessable income and assets to work out what you'll pay toward aged care, and it uses many of the same rules that determine your Age Pension rate. Services Australia applies deeming rules to financial assets (treating them as earning a set rate of income regardless of actual returns) and exempts your principal home up to a capped value when you have a protected person still living there.
- Complete the relevant form: SA456 for a combined income and assets assessment, SA457 if you only need an assets assessment, or SA485 if a representative is completing it on your behalf.
- Submit supporting documents (bank statements, super balances, investment details) as requested by Services Australia or the Department of Veterans' Affairs.
- Receive your fee advice letter, which according to My Aged Care's means assessment guidance remains valid for 120 days from the date it's issued.
- Use that letter when negotiating accommodation and ongoing fees with a provider, and request a review if your circumstances change materially before the letter expires.
Because the same income and assets figures feed into both your aged care fees and your Age Pension entitlement, a decision that lowers one (say, spending down liquid assets on a RAD) can shift the other. This is where the aged care and pension calculations genuinely intersect, and it's worth reading how Age Pension assets test thresholds work before locking in a strategy.
Practical planning checklist and timing: what to do and when
Getting the sequence right avoids the two most common mistakes: locking in an accommodation payment before understanding its effect on your pension, and letting a fee advice letter lapse mid-negotiation.
- Gather bank statements, superannuation statements, investment summaries and any Centrelink or DVA correspondence first.
- Complete your means assessment (SA456 or SA457) as early as possible, since it takes time to process.
- Use the My Aged Care fee estimators to model RAD, DAP and Support at Home scenarios before you need a decision.
- Get written fee quotes from any provider you're considering, and compare them against your fee advice letter.
- Book an adviser conversation before signing an accommodation agreement, not after, since the RAD or DAP choice affects both cashflow and the pension.
- Remember your fee advice letter is only valid for 120 days, so time major decisions within that window.
How to choose a financial adviser for aged care: checks, fees and questions to ask
Not every financial adviser handles aged care regularly, and the stakes (irreversible accommodation payments, pension implications, family dynamics) mean credentials matter. MoneySmart's guidance on choosing a financial adviser recommends checking the financial advisers register to confirm the person holds an Australian Financial Services (AFS) licence and asking for a Financial Services Guide (FSG) before any advice is given.
Fee structures vary. MoneySmart's breakdown of financial advice costs describes a Statement of Advice (SOA) fee for the initial plan, an implementation fee, ongoing or asset-based fees, and sometimes hourly rates. For a closer look at how these stack up in dollar terms, see this guide to adviser fee structures.
- Ask whether the adviser specialises in aged care or treats it as a small part of broader retirement work.
- Request the full fee schedule in writing before agreeing to anything.
- Ask how they'd structure a RAD versus DAP decision given your specific pension position.
- Treat a guaranteed outcome, vague fees, or no FSG as a red flag.
Pro Tip: Ask every adviser you interview the same five questions and compare the written answers side by side, not just the verbal pitch.
Amber Wealth: how we approach aged care financial advice
Amber Wealth is led by Adam Sobczak, Director and Senior Financial Planner, and works with pre-retirees and retirees across Melbourne on retirement planning that often includes aged care decisions. Our approach looks at Age Pension strategy, superannuation structure and accommodation payment choices together, since each one affects the others, rather than treating aged care as a standalone transaction.
Tax implications of aged care payments and financial advice
A RAD itself isn't taxed as income, but it's generally treated as an exempt asset for Age Pension purposes in specific circumstances, which is why timing a lump sum payment matters. Ongoing care fees, including the basic daily fee and means-tested contributions, are paid from after-tax income or assets and aren't typically deductible as a personal expense.
Where things get more complex is around drawing down superannuation or selling assets to fund accommodation payments. Withdrawing from an account-based pension can affect assessable income for both tax and means-testing purposes, and selling an investment property to fund a RAD may trigger capital gains tax considerations depending on how the property was held. Fees paid to a financial adviser for aged care advice may be deductible in some cases depending on what the advice relates to, but this depends on individual circumstances and is a matter for your tax adviser or accountant to confirm.
Because aged care fees, Age Pension entitlements and tax outcomes are calculated using overlapping but distinct rules, a decision that looks efficient from one angle (like paying a RAD in full) can have flow-on tax or pension effects that aren't obvious upfront. This is a reasonable point to get personalised advice rather than relying on general rules of thumb.
Procedures and timelines for applying for aged care subsidies and government benefits
Applying for aged care support starts with an assessment through My Aged Care, which determines what level of care you're eligible for, separate from the financial means assessment that sets your fees. Once you have an approved care need, you can move to arranging a provider and, in parallel, lodging your means assessment forms (SA456, SA457 or SA485) with Services Australia or DVA.
Processing times for means assessments vary depending on how complete your documentation is, which is why gathering statements and records early matters more than most people expect. Once issued, your fee advice letter is valid for 120 days, so there's a practical window to finalise provider agreements and any subsidy arrangements before needing a fresh assessment.
If your income or assets change meaningfully during that window (a property sale, an inheritance, a shift in super balance) you can request a reassessment rather than waiting for the letter to expire. Keeping this sequence straight, care assessment first, financial means assessment in parallel, provider agreement once both are settled, avoids the common problem of signing an accommodation agreement based on an outdated fee estimate.

Impact of aged care financial decisions on family members and potential inheritance
Decisions about how to fund aged care rarely affect only the person moving into care. A RAD paid from the family home's sale proceeds, for example, changes what's left in the estate, and family members sometimes have strong views about whether the home should be sold, rented out, or kept for now.
Gifting assets to family before a means assessment is a particular pressure point. Services Australia applies gifting rules that count gifts above a certain threshold as assessable assets for a period, so a well-intentioned transfer to help a grandchild or adult child can still affect the means assessment outcome. This is worth discussing openly with family before any transfers happen, not after.
There's also a practical conversation worth having early: who holds enduring power of attorney, who will manage ongoing provider relationships, and how any refundable deposit will be distributed if care arrangements change. These aren't just financial questions, but getting the financial side right (through a proper means assessment and a clear accommodation agreement) removes one layer of uncertainty from what's often an already difficult family discussion. Estate planning advice can help align these decisions with a broader will and asset strategy.
Common financial scams and fraud risks targeting elderly in aged care settings, and how to avoid them
People navigating aged care decisions, often under time pressure and emotional strain, are a target for scammers. Common approaches include unsolicited calls claiming to be from Centrelink or My Aged Care asking for personal or banking details, fake "aged care advisers" pressuring a quick decision on accommodation payments, and investment schemes pitched specifically at people who've just received a lump sum RAD refund.
A few habits reduce the risk substantially. Never give bank details or Centrelink reference numbers to someone who called you unprompted, even if they sound official, call Services Australia back on a verified number instead. Treat any adviser who guarantees a specific investment return or pressures you to sign on the spot as a warning sign, since MoneySmart's adviser guidance is clear that legitimate advisers operate under an AFS licence, provide a Financial Services Guide, and give you time to consider advice in writing.
If a family member has recently moved into care or received a RAD refund, it's worth having a trusted person review any unsolicited financial approaches with them, particularly in the weeks after a large sum of money has become liquid.
What practitioners see go wrong most often
In practice, the costliest errors aren't the fee calculations themselves but the timing: signing an accommodation agreement before the means assessment comes back, gifting assets without checking the rules first, or drawing down super without checking the pension effect. Getting assessed early, before any decision, is the simplest way to avoid all three.
— Adam
How Amber Wealth can help
If your aged care situation involves superannuation drawdowns, an Age Pension strategy, or decisions that affect your broader estate, a single conversation can bring these together rather than solving each piece separately. Amber Wealth offers retirement planning, Age Pension strategies, superannuation advice and insurance reviews for Melbourne clients and, where appropriate, clients across Australia.
- Retirement planning that factors in accommodation payment choices and ongoing care fees.
- Age Pension strategy work to understand how a RAD, DAP or asset sale affects entitlements.
- Superannuation and investment reviews to fund care costs without unnecessary tax drag.
- Insurance reviews where existing cover needs to be checked against changing circumstances.
This article is general information only and doesn't account for your personal circumstances. A complimentary conversation with Amber Wealth is a reasonable next step if you'd like advice tailored to your situation.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Schedule of fees and charges for residential care — Department of Health (20 Sep 2026)
- MoneySmart — choosing a financial adviser
FAQ
How much does aged care financial advice cost?
Costs vary by adviser and typically include a Statement of Advice fee, an implementation fee, and either ongoing or asset-based fees, as described in MoneySmart's financial advice costs guidance. Current prices are available on the client's pricing page.
What is the best financial advice for seniors?
There's no single best approach, since it depends on your assets, pension status and family situation, but MoneySmart recommends starting with a properly licensed adviser who provides a Financial Services Guide. Pairing that with a completed means assessment through My Aged Care gives any adviser the right numbers to work from.
What is the 2 year rule for aged care?
This commonly refers to gifting rules, where Services Australia counts certain gifts made in the past five years (not two) toward your assessable assets if they exceed the allowable threshold. Definitions and timeframes for gifting rules vary by context, so it's worth confirming the current thresholds directly with Services Australia or a financial adviser before transferring assets.
How can I legally reduce assets for aged care?
There's no blanket way to reduce assessable assets without consequence, since gifting above the allowable threshold is still counted toward your means assessment for a period. Legitimate strategies depend entirely on individual circumstances, which is why this is a question for a licensed financial adviser rather than a general rule.
Recommended
- Deeming rates 2026: what retirees need to know
- $218 Free Area From July 2026, Model Both Tests to Protect Age Pension
- Age pension assets test: July 2026 thresholds explained
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here. General Advice Warning Disclaimer: The information on this website is general information only and is not intended to be a recommendation. We strongly recommend you seek advice from your financial adviser as to whether this information is appropriate to your needs & financial situation.